
Reserve managers to ‘reconnect’ with their central bank, says Bill Allen
Central Banking On Air debate considers use of securities lending strategies
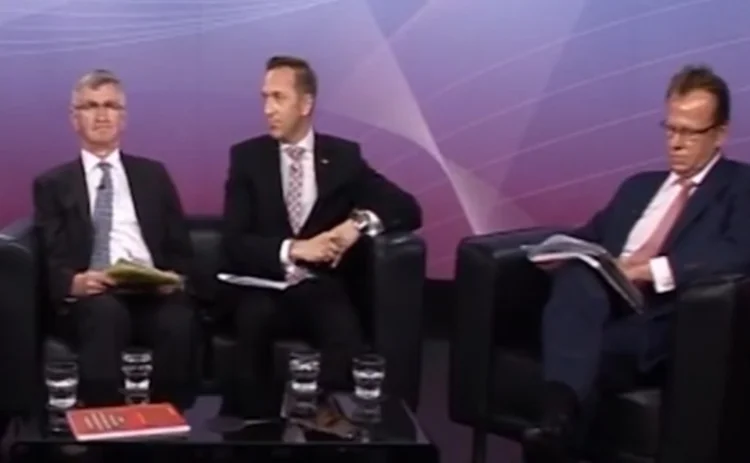
Top executives at central banks will become "more conscious" of the relationship between the activities of their reserve managers and financial stability issues in the wider economy in the coming years, according to Bill Allen, a former deputy director at the Bank of England.
Allen, a participant in the latest Central Banking On Air debate, Optimising returns from central bank reserves, believes the growing responsibility central banks have for financial stability will affect how reserve managers operate.
"In the past, reserve management has been an activity pretty much separate from the rest of central banking," he says, "and I think that's going to have to change. I think it will change."
Allen, now a visiting senior fellow at Cass Business School, also predicts that central banks will focus more on the "ultimate objectives" of reserve holding. He stresses they will have to be "pretty rigorous in maintaining liquidity" within their portfolios.
Another participant in the debate, Róbert Rékási, the head of foreign exchange reserves management at the Central Bank of Hungary, identifies a "triangle" of objectives: liquidity, safety and return.
Rékási says that, since the financial crisis, reserve managers have placed "more emphasis" on returns because of the low-yield environment. "We are chasing every basis point that we can earn," he says.
One popular way of generating return is through securities lending, whereby the central bank will lend another market participant a security in return for collateral in the form of shares, bonds or cash. The borrower will also pay a fee for the loan.
John Arnesen, the global head of agency securities lending market and financing services at BNP Paribas Securities Services, argues that "almost every regulator" considers securities lending "a well-established practice that adds liquidity to the system".
Central banks, he says, have engaged in the practice since the 1980s. "I find there is sometimes an almost altruistic approach from central banks," he says. "They understand that liquidity addition, and I think they almost feel a responsibility to engage in releasing their assets into the market for those purposes."
Allen identifies three risks involved in securities lending: that the central bank will fail to get its securities back; that it will "give up" liquidity in the process; that it will create a macro-prudential issue.
"What you've really got here is reserve managers providing liquidity to broker-dealers, to banks trying to build up their own liquidity," he says. "Commercial banks are meeting the LCR [liquidity coverage ratio] in effect by borrowing from central banks. Not their own central banks, but foreign central banks."
Rékási says this was simply "part of the business" and the central bank is "giving up something to get something". Arnesen suggests the financial crisis made central banks more alert to the risk they were taking on.
"Prior to 2007, typically I had central banks generating a huge amount of revenue from securities lending. They were very appreciative of it and didn't ask many other questions than that," Arnesen says.
"Today we have a situation where the questions are: "I understand you've generated revenue, but I want to know how. What did you have to do? What is the risk-adjusted return you are making?
"They understand they are engaged in this transformation, receiving something that is funding the positions of broker dealers. They get that, and they want to be paid for that."
He singles out "reputation risk" as one of central banks' main concerns. "They are probably held to a higher account in some ways," he says. "If they are going to be engaged actively in the investment management process, they want it to be seen to be the smoothest operation possible."
Only users who have a paid subscription or are part of a corporate subscription are able to print or copy content.
To access these options, along with all other subscription benefits, please contact info@centralbanking.com or view our subscription options here: www.centralbanking.com/subscriptions
You are currently unable to print this content. Please contact info@centralbanking.com to find out more.
You are currently unable to copy this content. Please contact info@centralbanking.com to find out more.
Copyright Infopro Digital Limited. All rights reserved.
As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (point 2.4), printing is limited to a single copy.
If you would like to purchase additional rights please email info@centralbanking.com
Copyright Infopro Digital Limited. All rights reserved.
You may share this content using our article tools. As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (clause 2.4), an Authorised User may only make one copy of the materials for their own personal use. You must also comply with the restrictions in clause 2.5.
If you would like to purchase additional rights please email info@centralbanking.com
More on Reserves
Reserve Benchmarks 2026 – model banks analysis
Additional data breakdowns shed light on AI use, liquidity lines and FX interventions
SNB could unwind tiering, but gain ‘not obvious’, Martin says
Vice-chairman defends Switzerland’s tiered approach to ample reserves
Gold is a good diversification strategy for central banks – Nagel
Geopolitical and credit risks strengthen case for bullion as reserve asset, says Bundesbank president
Reserve Benchmarks 2026 – executive summary
Data reveals diversification trend and sheds light on AI use in reserves management
Reserve Benchmarks 2026 report – investing in uncertain times
Benchmarks highlight trend towards diversification, AI use and a modest response to tariffs
Swap lines with PBoC outnumber those with ECB by factor of three
Benchmark respondent complains of limited access to dollar swaps
Quarter of central banks adjusted reserves strategy after tariffs
Managers mostly adjusted duration; most change comes from Asia-Pacific
Third parties manage roughly one-sixth of reserves
Compensation for external asset managers takes different forms across jurisdictions