
ECCB persuades states to relax fiscal stance
IMF supports move to deal with pandemic’s effects, warning against “drastic fiscal consolidation”
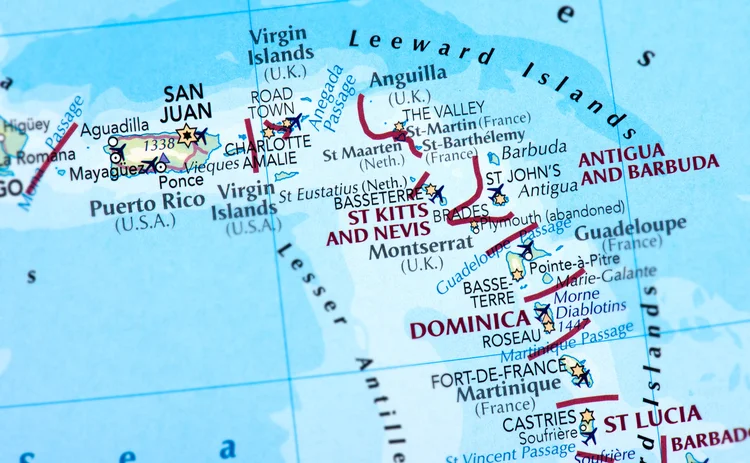
The Eastern Caribbean Central Bank has successfully recommended that the eight island states it serves loosen their fiscal restraints to deal with the Covid-19 pandemic.
The ECCB’s monetary council accepted a recommendation from the central bank governor that the eight members postpone the date for achieving their targeted “fiscal anchor”. ECCB members will now aim to reduce their total debt to 60% of collective GDP by 2035 rather than by 2030, the council announced on February 12. The move was supported by a staff statement from the International Monetary Fund.
The ECCB is the central bank for the eight members of the Eastern Caribbean Currency Union, and has been led by governor Timothy Antoine since February 2016. Antoine succeeded Dwight Venner, who had held the role from 1989 to 2015.
Six ECCU members are countries: Antigua and Barbuda, Dominica, Grenada, Saint Kitts and Nevis, Saint Lucia, and Saint Vincent and the Grenadines. The other two, Anguilla and Montserrat, are British Overseas Territories. Between them, the ECCU members have a population of approximately half a million.
The ECCB’s monetary council is made up of the finance minister from each of the eight ECCU member states. The monetary council said the ECCB had recommended shifting the date “in the face of the largest growth shock, on record, occasioned by the Covid-19 pandemic”.
The council also agreed to cut one of its three policy rates, lowering the long-term credit rate from 6.5% to 3.5%. It decided to keep the minimum saving rate at 2% and the discount rate at 2%.
This is the second time the ECCU has agreed to relax the “fiscal anchor”. The ECCU first adopted the measure in 2003, aiming to achieve the target ratio of 60% by 2020. It then postponed that date to 2020 in February 2015 to help deal with the recession that followed the global financial crisis.
“Fiscal anchor”
On the same day as the decision, the IMF took the unusual step of publicly supporting the relaxation of the “fiscal anchor”. The IMF said in a staff statement that the 60% ratio had “served as an important fiscal anchor for the ECCU”.
But the statement warned that “meeting the target is no longer feasible for several countries in the region without drastic fiscal consolidation”. This “would be ill-advised as it would both slow the recovery from the pandemic and constrain long-term growth prospects through scarring”, the IMF statement said.
But it cautioned that the move “puts the onus on countries in the ECCU to further enhance their fiscal responsibility frameworks to boost market confidence”. The IMF statement also warned that “financial system risks are gradually increasing” in the ECCU.
The IMF warned of increasing risks for the ECCU’s financial sector, after praising the handling of the pandemic’s initial impact by the ECCB and national authorities. The pandemic was expected to reduce borrowers’ ability to service debt.
The pandemic could “start eroding banks’ and credit unions’ deposit-based funding as the existing support initiatives expire”, the IMF staff said. Most ECCB-based banks had “sizeable pre-pandemic capital and liquidity buffers”, but these were likely to be worn down by the pandemic, especially for institutions with concentrated asset exposures.
IMF warns of vulnerability
The IMF statement called for reforms to how ECCU countries handle fiscal decisions, “given the ECCU’s vulnerability to external shocks”. The region is heavily dependent on tourism for foreign currency earnings and has been severely affected by hurricanes.
ECCU countries should create common standards and arrangements for national fiscal responsibility frameworks and regional fiscal oversight bodies, the IMF said. It noted that some ECCU members had “accelerated progress toward adopting a full-fledged rules-based fiscal framework”.
The IMF said authorities needed to support these measures by improving their budget processes, fiscal forecasting and debt sustainability analysis.
They also needed to create “national disaster resilience strategies” to be able to better cope with the economic impact of climate-related shocks. The IMF also recommended that the ECCU members develop sovereign debt instruments to support their fiscal sustainability.
Only users who have a paid subscription or are part of a corporate subscription are able to print or copy content.
To access these options, along with all other subscription benefits, please contact info@centralbanking.com or view our subscription options here: www.centralbanking.com/subscriptions
You are currently unable to print this content. Please contact info@centralbanking.com to find out more.
You are currently unable to copy this content. Please contact info@centralbanking.com to find out more.
Copyright Infopro Digital Limited. All rights reserved.
As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (point 2.4), printing is limited to a single copy.
If you would like to purchase additional rights please email info@centralbanking.com
Copyright Infopro Digital Limited. All rights reserved.
You may share this content using our article tools. As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (clause 2.4), an Authorised User may only make one copy of the materials for their own personal use. You must also comply with the restrictions in clause 2.5.
If you would like to purchase additional rights please email info@centralbanking.com
More on Financial Stability
As NBFI sector grows, so do its risks and benefits – Knot
Former FSB chair discusses implications of sector’s increasing dominance
Kansas City Fed warns of long-term AI financing risks
Highly leveraged entities may cause financial stress to spill over to broader economy

IMF flags gaps in Somalia’s financial reform efforts
Fund notes progress, but says central bank should go further to safeguard stability
Divergence from global cycles gives Asia policy room – Amro
Change may allow Asean+3 central banks to focus on domestic rather than global conditions, report says
BIS’s Hernández de Cos on AI, non-bank risk and tokenisation
General manager talks about how the BIS is navigating a complex global environment
RBA says stability risks mainly come from abroad
Bank’s finstab report says financial system resilient but points to AI and geopolitical concerns
Supervisors must co-operate internationally – Elderson
ECB board member warns emerging risks to stability demand joint response from regulators

Bailey calls for AI kill switch ahead of regulation
FPC says technology is escalating financial stability risks and making them more intertwined