
Foreign exchange origins of Japan's economic slump
AUTHOR'S ABSTRACT
Japan's macroeconomic problem has yet to be properly diagnosed. Throughout the 1990s, policy makers could not decide on the proper macro economic measures to combat the country's severe economic slump. We propose a unified explanation, with deep historical roots, of why aggregate private demand failed to recover after Japan's stock and real estate bubbles burst in 1991 and deflationary pressure continues.
The problem is not purely 'made in Japan'. It arises from Japan's unbalanced mercantile relationship with the United States. Starting in the early 1970s, numerous trade disputes between the two countries created tensions that were (temporarily) resolved by the yen going ever higher against the dollar up to 1995. In the last two decades, this persistent pressure for the yen to rise was further aggravated by Japan's large current-account (saving) surpluses as the counterpart of America's large current account (saving) deficits. The legacy is the expectation that trade and financial tensions will recur so that the yen will be higher 10, 20, or 30 years from now -with Japan's (wholesale) price level forced correspondingly lower and nominal interest rates on yen assets remaining more than four percentage points less than those on dollar assets.
This fear of yen appreciation, whose timing is erratic and unpredictable, now inhibits private domestic investment by both Japanese firms and households. Our theory also explains why, in the late 1990s, nominal interest rates on short-term yen assets were compressed toward zero so as to destroy the normal profit margins of the banking system. In this liquidity trap, the Bank of Japan -whose monetary policy has been quite 'expansionary' -is powerless to stimulate the flagging economy.
To spring the liquidity trap, eliminate deflationary pressure, and restore macro economic balance in Japan, the American and Japanese governments must act jointly to quash the expectation that the yen will be higher in the future than it is today.
The article is in World Economy journal, Volume 24: Issue 3.
Only users who have a paid subscription or are part of a corporate subscription are able to print or copy content.
To access these options, along with all other subscription benefits, please contact info@centralbanking.com or view our subscription options here: www.centralbanking.com/subscriptions
You are currently unable to print this content. Please contact info@centralbanking.com to find out more.
You are currently unable to copy this content. Please contact info@centralbanking.com to find out more.
Copyright Infopro Digital Limited. All rights reserved.
As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (point 2.4), printing is limited to a single copy.
If you would like to purchase additional rights please email info@centralbanking.com
Copyright Infopro Digital Limited. All rights reserved.
You may share this content using our article tools. As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (clause 2.4), an Authorised User may only make one copy of the materials for their own personal use. You must also comply with the restrictions in clause 2.5.
If you would like to purchase additional rights please email info@centralbanking.com
More on Monetary Policy

Inflation fears prompt Pakistan to tighten policy by 50bp
Although price growth has eased slightly, it remains well above 5–7% target range
Arcontech enhances central banks’ market‑sensitive data publishing with end-to-end encryption
Monetary policy decisions and auction results are safeguarded against cyber security threats.

Lagarde sees slower pass-through after bond sell-off
Higher yields will limit knock-on effects from energy shock, ECB president tells IMF meeting
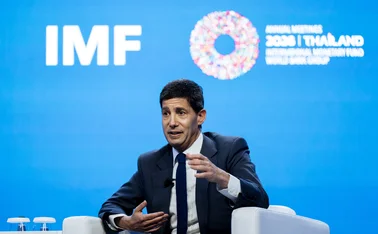
Warsh: I’ve focused too much on monetary policy
Fed chair vows to pay more attention to supervision, payments systems and consumer affairs

Little evidence of second-round inflation in UK – Bailey
BoE governor says economy more resilient than expected, amid signs of AI investment
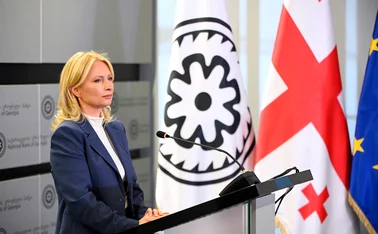
Pre-emptive policy has built credibility, says Georgian governor
Enriched monetary policy toolkit assesses whether shocks are transitory in a volatile world

Fiscal consolidation still possible in France – Moulin
BdF governor says Europe facing twin shock from surge in energy costs and bond yields

Singapore surprises with pause in tightening cycle
MAS says decision made against backdrop of rising inflation, but expects price growth to slow next year