
Argentina sells dollars in parallel FX market
Domestic currency’s CCL value jumps as central bank tightens monetary supply
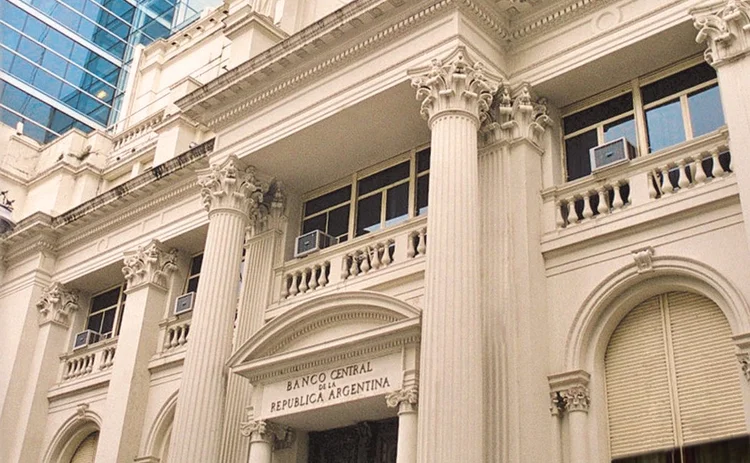
The Central Bank of Argentina (BCRA) on July 15 began selling US dollars in a parallel foreign exchange (FX) market as part of the authorities’ efforts to tackle the country’s persistently high inflation.
Economy minister Luis Caputo announced the measure last week. In a posting on social media, he stated that if the BCRA bought dollars on the official foreign exchange market, the injection of equivalent pesos into the monetary supply would be counteracted through the sale of an equivalent amount of dollars in the blue-chip swap (contado con liquidacion, or CCL) market.
CCL is one of Argentina’s unofficial exchange rates. It is determined by investors buying securities in Argentina and selling them in the US, which creates an implied exchange rate.
The peso’s CCL value closed at 1405 to the dollar on July 12 and jumped to 1291 pesos following the start of the BCRA’s operation, according to Bloomberg. This brings the parallel exchange rate closer to the official rate of 919 pesos to the dollar.
Caputo said the official exchange rate would remain the same and that the central bank’s operation would “deepen” the disinflation process.
Risky operation
Georgina Gómez, an associate professor at Erasmus University Rotterdam, tells Central Banking the intervention is “quite a risky measure” aimed at calming down the FX markets.
She says selling dollars in the parallel market implies there has been an additional, and significant, depletion of the BCRA’s already-scarce reserves.
Gómez adds that the measure will also reduce the speed at which the central bank could buy dollars on the official market, and that the risk premium on Argentine bonds has already gone up because of this operation.
“How sustainable is this? In my opinion, [it can’t go on] for long,” Gómez says.
Arturo Porzecanski, an economist and a research fellow at American University in Washington DC, agrees the central bank’s operation was a “risky move”.
“The BCRA will remove pesos from circulation and make a tidy profit from the arbitrage – but at the expense of missing out on the opportunity to rebuild its international reserves,” he tells Central Banking.
Porzecanski adds that the intervention implies that the official exchange rate is likely to remain grossly overvalued even longer than was previously expected, and foreign bondholders will raise concerns of a sovereign default in 2025. Any attempt by the government to switch from the peso to the dollar – the stated intent of president Javier Milei following his election last December – will also need to be further postponed, he says.
Slowing inflation and IMF support
Annual inflation in Argentina is currently 271.5%. However, monthly inflation has been falling this year, largely due to the austerity measures pursued by Milei.
Gómez notes that the BCRA’s intervention is the latest in a series of measures aimed at curbing inflation, but its impact is “bound to be minimal”. Porzecanski thinks the intervention is likely to result in a further reduction in monthly inflation, though again the impact will only be minimal.
In June, the International Monetary Fund (IMF) acknowledged the government’s progress on disinflation during the eighth review of the $44 billion extended fund facility that Argentina signed with the institution in 2022.
The successful conclusion of the review enabled the IMF to disburse another $800 million to the country to “support the authorities’ efforts to entrench the disinflation process, rebuild fiscal and external buffers and underpin the recovery.”
“Monetary and FX policies need to evolve to continue to entrench the disinflation process and further improve reserve coverage,” the IMF stated.
Only users who have a paid subscription or are part of a corporate subscription are able to print or copy content.
To access these options, along with all other subscription benefits, please contact info@centralbanking.com or view our subscription options here: www.centralbanking.com/subscriptions
You are currently unable to print this content. Please contact info@centralbanking.com to find out more.
You are currently unable to copy this content. Please contact info@centralbanking.com to find out more.
Copyright Infopro Digital Limited. All rights reserved.
As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (point 2.4), printing is limited to a single copy.
If you would like to purchase additional rights please email info@centralbanking.com
Copyright Infopro Digital Limited. All rights reserved.
You may share this content using our article tools. As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (clause 2.4), an Authorised User may only make one copy of the materials for their own personal use. You must also comply with the restrictions in clause 2.5.
If you would like to purchase additional rights please email info@centralbanking.com
More on Monetary Policy

Lagarde sees slower pass-through after bond sell-off
Higher yields will limit knock-on effects from energy shock, ECB president tells IMF meeting
Warsh: I’ve focused too much on monetary policy
Fed chair vows to pay more attention to supervision, payments systems and consumer affairs

Little evidence of second-round inflation in UK – Bailey
BoE governor says economy more resilient than expected, amid signs of AI investment
Pre-emptive policy has built credibility, says Georgian governor
Enriched monetary policy toolkit assesses whether shocks are transitory in a volatile world

Fiscal consolidation still possible in France – Moulin
BdF governor says Europe facing twin shock from surge in energy costs and bond yields

Singapore surprises with pause in tightening cycle
MAS says decision made against backdrop of rising inflation, but expects price growth to slow next year
BoK to review use of dot plot it debuted this year – Shin
Governor aims to find forward guidance ‘sweet spot’ and says any review will wait until at least next year
Monetary policy must be more agile during AI transition – study
Bank of Italy paper says inflationary developments offer more reliable guide than long-term r*