
South Africa in fresh attempt to curb rand volatility
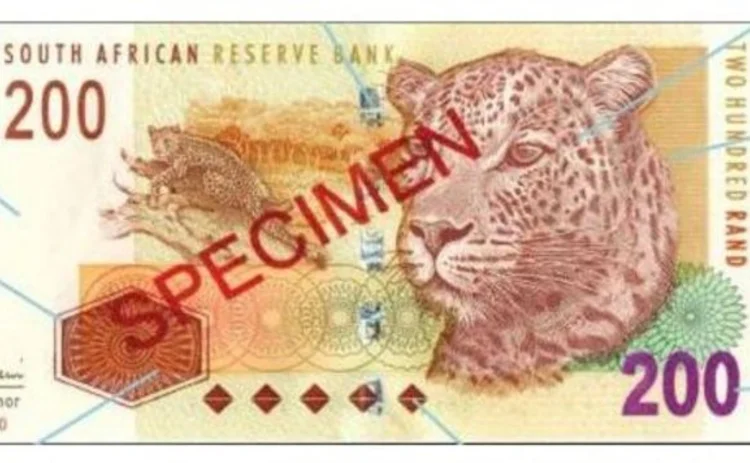
South Africa's ruling African National Congress (ANC) party is set at the end of September to consider a short-term capital inflows tax to remedy the volatility of the rand.
In a discussion document for the party's national general council, to be held near the end of next month, the ANC flagged the problem posed by capital inflows, sparked by increased foreign purchases of South African bonds and equities, as global risk appetite returns. By pushing up the value of the rand, inflows have subsidised the cost of imports by lowering the price of goods such as clothing, food and petrol. However, they have also had a hand in decreasing the competitiveness of South African exports. The rand has fluctuated over the course of the year. It hit a low of R7.908 to the dollar on 25 May, but traded at R7.286 to the greenback at 11:30 London time on Tuesday.
Local businesses have also suffered as cheap imports have limited demand for South African goods in the country, the ANC said. The party considers the debate on taxing short-term capital flows to a key one, given the wide support, from South Africa's manufacturers, for a weaker currency.
While the South African Reserve Bank (Sarb) is not impervious to businesses' concerns, officials have expressed reservations about interfering with rand levels- the intended outcome of a short-term inflows tax. In a June interview in Basel, Gill Marcus, the governor of the Sarb, told CentralBanking.com that although the central bank understood manufacturer's worries about the strength of the currency, it was not about to meddle with free-market forces. "If you're a manufacturer, then you are going to see [the rand's strength] as a problem, and we are concerned about that. But there's no simple answer," she said. "Greece is estimated to have lost 30% of its competitiveness because its membership of the euro area effectively means that it has a fixed exchange rate," Marcus added. The central bank declined to comment on the contents of the discussion document.
Pravin Gordhan, the South African finance minister, has also defended the country's flexible exchange rate regime.
"We agree with the Treasury's view that a tax on short-term speculative flows needs to be carefully considered, given South Africa's still heavy reliance on these flows to finance its current account deficit, owing to the country's poor savings record," said Jeff Gable, Ian Marsberg and Jeffrey Schultz, analysts at Absa Capital, a subsidiary of Barclays, a bank. "A weaker currency also needs to be taken in the context of the possible negative implications for inflation," they added.
Revisiting the inflation targeting debate
The ANC's discussion document also reopens the inflation targeting divide, suggesting that the framework is responsible for interest rates in South Africa which are higher than in developed economies. "Fiscal policy has been reasonably expansionary, as measured by the growth in expenditure for most of [the last decade], and strongly countercyclical since 2008," the ANC said. "But debates remain as to whether monetary policy has been sufficiently supportive of equitable growth."
The Sarb pushed hard for the adoption of inflation targeting, finally succeeding in February 2000, against resistance from members of the ANC. Marcus said in June that there was no question as to whether the framework had benefitted South Africans. "High prices and inflation are bad for the poor, and if your society understands that, then they accept the measures that you take," she said. As in the rand debate, here too, the government has supported the Sarb's position, with Gordhan in July praising the framework for providing investors with "confidence in times of crisis," and giving the central bank the flexibility it needs.
Only users who have a paid subscription or are part of a corporate subscription are able to print or copy content.
To access these options, along with all other subscription benefits, please contact info@centralbanking.com or view our subscription options here: www.centralbanking.com/subscriptions
You are currently unable to print this content. Please contact info@centralbanking.com to find out more.
You are currently unable to copy this content. Please contact info@centralbanking.com to find out more.
Copyright Infopro Digital Limited. All rights reserved.
As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (point 2.4), printing is limited to a single copy.
If you would like to purchase additional rights please email info@centralbanking.com
Copyright Infopro Digital Limited. All rights reserved.
You may share this content using our article tools. As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (clause 2.4), an Authorised User may only make one copy of the materials for their own personal use. You must also comply with the restrictions in clause 2.5.
If you would like to purchase additional rights please email info@centralbanking.com
More on Monetary Policy
BoJ raises rates to 31-year high
Ueda says ‘policy phase has changed’ and focus now is on ensuring inflation does not exceed 2%
Czech Republic extends pause while Moldova raises rates
CNB leaves door open to rate rise while Moldova presses on with third hike since May
BoE holds rates and reveals talks to sell gilts to Treasury
Economists voice concerns over blurred fiscal and monetary policies
Federal Reserve delivers first rate hike since 2023
FOMC expects policy to remain around 4.1% for 2026–27 and inflation to reach 2% by 2029

Geopolitical tensions raising rate hike expectations – BIS
Quarterly review highlights new communication challenges for central banks
Middle East conflict will prolong inflation shock, Lagarde says
ECB chief warns AI is also driving long-term funding costs for governments

Naji Issa on Libya’s reform efforts and why he threatened to quit
The CBL governor speaks about the need for national unity, fiscal responsibility, digital transformation and FX reforms

The Fed enters a new epoch
Chair Kevin Warsh takes his first steps to transform the US central bank